-
Related posts
-
What the 2026 Summer VAT reduction means for businesses ?
12 June 2026
-
What small companies need to know about the Companies House accounts filing changes
10 June 2026
-

Companies House changes to statutory filing fees from February 2026
29 January 2026
-
How will the annual ISA cash limit reducing to £12,000 from £20,000 impact me?
27 November 2025
-
How will the 2% increase in the tax rate affect my savings interest?
27 November 2025
-
How will the 2% increase in the tax rate for property income affect me?
27 November 2025
-
How will the upcoming changes affect me if I currently use the salary sacrifice scheme to make pension contributions?
27 November 2025
-
How will the 2% increase in the tax rate affect my dividend income?
27 November 2025
-
Review our Autumn Budget 2025 Summary
26 November 2025
-

How flexibility helped Jaimi Wilson thrive in work and explore her passion for adventure
19 November 2025
-
Tax relief on Christmas parties, what you can claim this festive season
16 October 2025
-

Verifying your identity with Companies House
17 September 2025
-

Simplifying accounting, so you can focus on farming
1 September 2025
-
What happens when you don’t have a Will in place?
4 August 2025
-

From student to specialist
17 July 2025
-
Client Spotlight: Meet the Peile Family, hosts of the 2025 NSA North Sheep
30 May 2025
-
What are accounting services and who needs them?
24 March 2024
-
Different scenarios to help illustrate the issues that can arise from an intestacy
14 November 2023
-
Research and Development (R&D) Tax Relief
4 January 2023
-
Our amazing Jaimi takes on Transiberica 2022
3 October 2022
-
Can I deal with probate myself?
11 August 2022
-
What is an excepted estate?
13 July 2022
-
Nurturing your future at David Allen
27 May 2022
-
Research and Development (R & D) Tax Relief
25 May 2022
-
What is Ethical Banking?
4 May 2022
-
I am an Executor of someone’s Will – what are my next steps?
28 April 2022
-
Mileage allowance versus the rising cost of fuel
20 April 2022
-
What is probate?
5 April 2022
-
When can a Bounce Back Loan become a personal liability?
9 March 2022
-
Corporation Tax rates are increasing. Will this affect your company?
3 March 2022
-
Our Estate Administration Costs Calculator
1 March 2022
-
How are cryptocurrencies taxed in the UK?
1 March 2022
-
Should I be VAT registered?
24 February 2022
-
New Year, New business?
19 January 2022
-
Making Tax Digital for Income Tax – Getting you ready
25 November 2021
-
Should you trade as a sole trader or limited company?
25 November 2021
-
When does a hobby become taxable?
16 November 2021
-
Getting to know clients Peter and Carol Johnston, John Watt and Son
1 October 2021
-
Super-deduction tax break – what is it and how does it work?
16 September 2021
-
Julie Taylor celebrates 15 years at David Allen
29 July 2021
-
New Accounts Apprentice joins David Allen Chartered Accountants, Dumfries.
12 July 2021
-
What is Probate and estate administration?
26 March 2021
-
How a great auditor can add value to your business
27 January 2021
-
The importance of having a Will in place
15 January 2021
-
Dealing with a loved one’s last wishes – probate and why using David Allen makes sense
19 November 2020
-
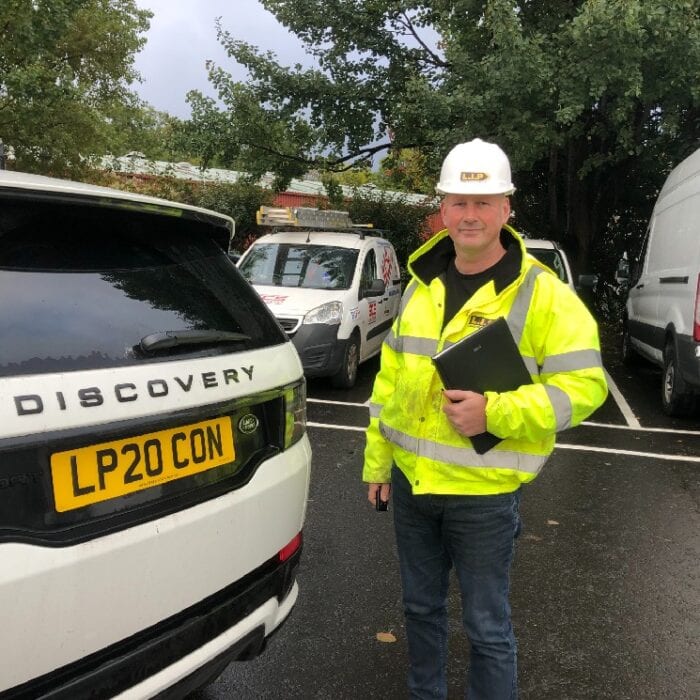
L.I.P. Construction Ltd are building their business with support from David Allen
13 October 2020

